
A delayed insurance claim in Port Arthur can be more exhausting than a denial. There is no clear answer to respond to, only unreturned calls, new adjusters, repeated document requests and a roof tarp that is wearing out. Some delay is normal after a major hurricane, when an insurer may be handling an enormous number of claims along the upper Texas coast at once. But Texas law does set timelines for claim handling, and a claim that has drifted well past them deserves attention. We help Port Arthur and Jefferson County property owners understand where their claim stands, organize the record and push the file toward a decision.
Texas Prompt Payment Timelines
The Prompt Payment of Claims provisions in Texas Insurance Code Chapter 542, Subchapter B set general deadlines for most insurers:
| Stage | General deadline | Section |
|---|---|---|
| Acknowledge the claim, begin the investigation and request needed information | 15 days after the insurer receives notice of the claim | §542.055 |
| Accept or reject the claim in writing | 15 business days after receiving all items the insurer requested | §542.056 |
| If more time is needed, notify the policyholder | Within the same 15 business days; decision then due within 45 more days | §542.056 |
| Pay an accepted claim | 5 business days after notifying the policyholder of acceptance | §542.057 |
| Weather-related catastrophe declared by the commissioner | Deadlines extended by an additional 15 days | §542.059 |
A few important qualifications. The 15-business-day clock for a decision starts after the insurer receives everything it reasonably requested, which is why the timing of document requests matters. Surplus lines insurers are treated differently. TWIA claims fall under their own rules in Chapter 2210; our TWIA windstorm claims page and our TWIA claim guide explain those. If you believe the statute has been violated, the remedies are a legal question for a Texas attorney.
Why Claims Stall After Gulf Coast Storms
- Catastrophe volume. After hurricanes such as Laura or Harvey, insurers and TWIA bring in temporary adjusters to handle claims across Southeast Texas and Southwest Louisiana.
- Adjuster turnover. Files are reassigned as catastrophe adjusters rotate out, and new adjusters may start over.
- Multiple policies. A homeowners carrier may wait on the TWIA or flood decision before acting, and vice versa.
- Open-ended requests. Requests for “additional documentation” without saying what is needed keep the decision clock from starting.
- Engineer and expert reports. Outside reports can add weeks, and the results are not always shared promptly.
- Disagreement in silence. Sometimes a claim is not delayed so much as stuck, because the adjuster disagrees with the scope but has not said so in writing.
How to Build a Record That Moves a Claim
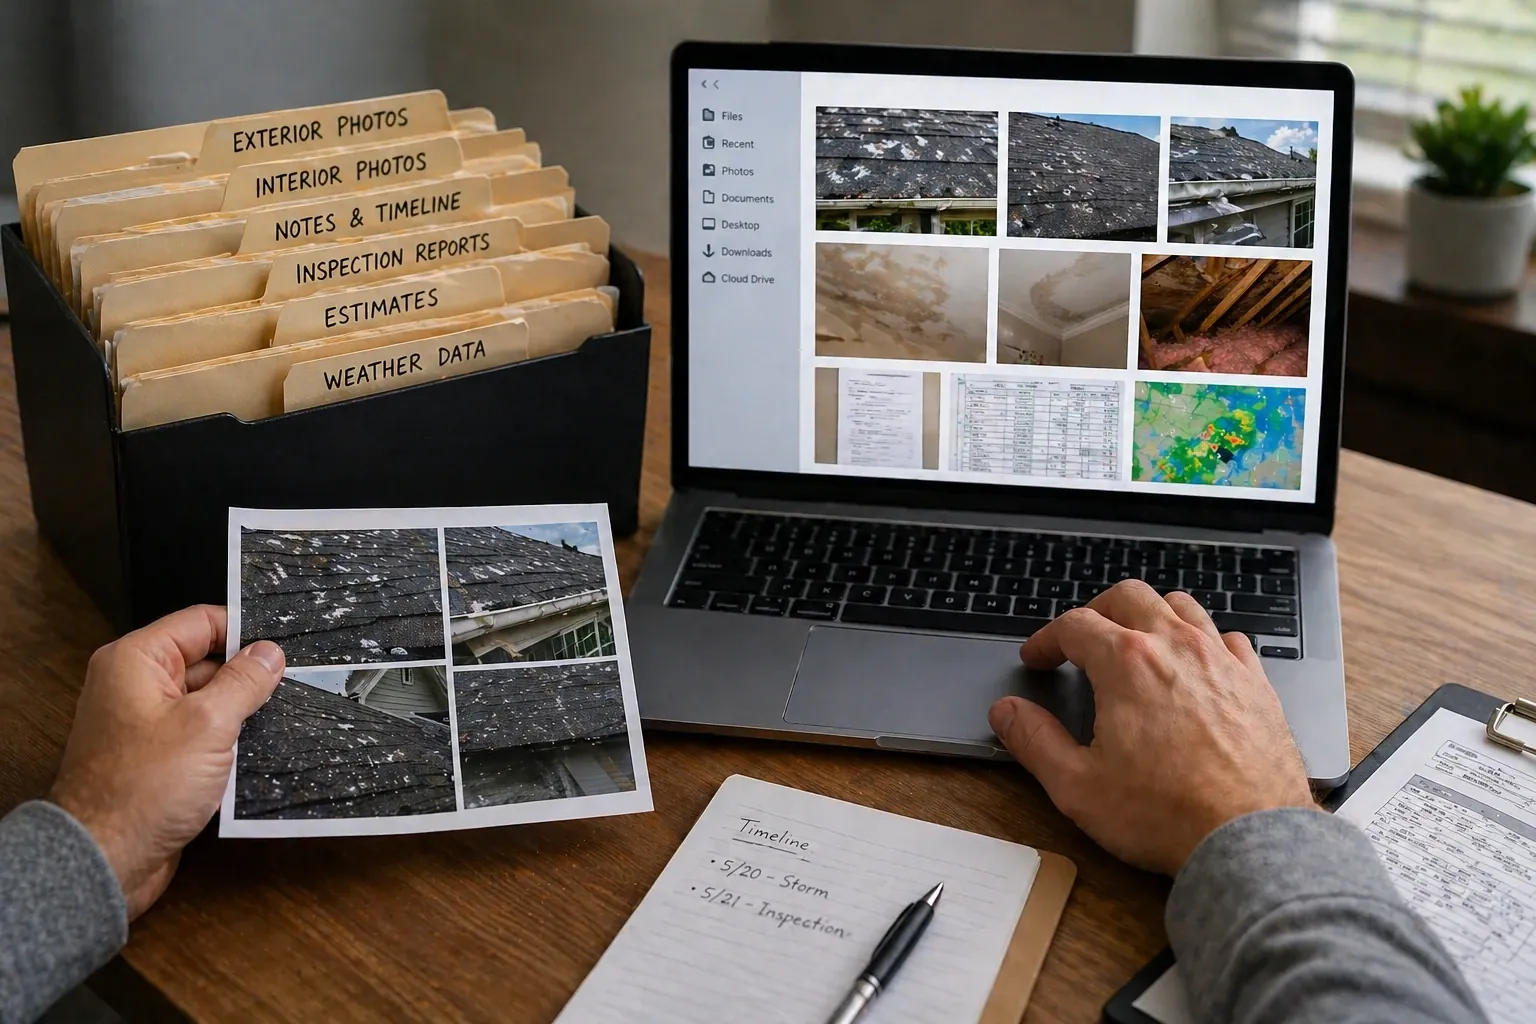
The single most effective thing a policyholder can do about delay is document it. A clear timeline turns “they’re dragging their feet” into specific dates that can be shown to the insurer, TDI or an attorney.
- Log every contact. Date, time, name, what was said and what was promised.
- Move important conversations to writing. After a phone call, send a short email confirming what was discussed.
- Ask what is missing. Request a written list of every item the insurer still needs to make a decision.
- Confirm delivery. Send documents in a way that shows the date received, and keep copies.
- Request status in writing. If a decision deadline has passed, ask in writing for the claim’s status and the reason for the delay.
- Keep protecting the property. Replace worn tarps, keep drying equipment running and photograph conditions over time.
Our claim documentation checklist and the article on documenting storm damage in Port Arthur cover the evidence side.
Delays on Flood and Multi-Policy Claims
Flood claims under the National Flood Insurance Program follow federal rules rather than the Texas Prompt Payment statute, including their own proof-of-loss requirements and deadlines. Check floodsmart.gov and your flood policy for the current requirements, and do not let a slow homeowners or TWIA claim cause you to miss a flood deadline. When several insurers are involved, it can help to keep a separate log for each claim, with its own claim number, adjuster, requests and deadlines. A single shared timeline is useful too, because each insurer’s decision may depend on what the others have found.
What Reasonable Delay Looks Like
Not every delay is improper. After a declared catastrophe, deadlines are extended, and complex losses, such as large commercial buildings or homes needing an engineer’s report, can legitimately take longer. The warning signs are different: no written acknowledgment, no clear list of what the insurer still needs, deadlines that pass without a request for more time, or months with no meaningful activity on the file.
When a Delay Becomes Something Else
Sometimes a long delay ends with a low offer or a partial denial. If that happens, the next step depends on what the insurer decided. An inadequate payment may call for an underpaid claim review and supplement; a disagreement over the amount may lead to appraisal; a coverage denial may require legal advice. Keep in mind that many Texas policies set a contractual deadline to file suit, often two years and one day, and that weather-related claim suits require written pre-suit notice under Chapter 542A. A slow claim does not pause those clocks, so talk with a Texas attorney if time is getting short.
How a Port Arthur Public Adjuster Can Help
When we take on a delayed claim, we start by reconstructing the timeline: when the claim was reported, what the insurer requested, what was provided and when. We fill documentation gaps, prepare a complete estimate if one does not exist and communicate with the adjuster in writing so the file has a clear record. As a Port Arthur Public Adjuster, we cannot force a decision or guarantee an outcome, but a well-organized claim with no open requests gives the insurer little reason to wait.
Fees are disclosed in a written contract before any work begins; Texas law caps public adjuster compensation at 10% of the insurance settlement. If your claim has stalled, request a Free Claim Review or call +1 (832) 503-5866.
Frequently Asked Questions
How long does an insurance company in Texas have to pay a claim?
Under the Prompt Payment of Claims provisions in Texas Insurance Code Chapter 542, an insurer generally has 15 days after notice to acknowledge and begin investigating, 15 business days after receiving all requested items to accept or reject (or say it needs more time, up to 45 more days), and 5 business days after accepting to pay. Deadlines are extended by 15 days after a declared weather-related catastrophe. Surplus lines insurers and TWIA follow different rules.
Does TWIA follow the same deadlines?
TWIA claims are governed by their own provisions in Texas Insurance Code Chapter 2210, with separate timelines for filing, accepting or denying, and disputing claims. Check twia.org and your policy for the current requirements.
The insurer keeps asking for more documents. Is that allowed?
Insurers may reasonably request information needed to evaluate a claim. Repeated requests for items already provided, or requests that do not relate to the loss, are worth documenting. Respond in writing, keep copies and note the date each item was delivered.
My adjuster changed three times. What should I do?
Ask each new adjuster to confirm in writing that they have the full file, including prior photos, estimates and correspondence. Send a short summary of where the claim stands and what is outstanding. That prevents the claim from restarting each time.
Can I file a complaint with TDI about a slow claim?
Yes. The Texas Department of Insurance accepts consumer complaints about claim handling. The insurer must respond to TDI, which sometimes helps move a stalled file.
What if the delay is causing more damage to my home?
Most policies require you to take reasonable steps to protect the property from further damage, such as tarping a roof or drying wet areas. Document what you do and keep receipts; reasonable mitigation costs are often part of the claim.