
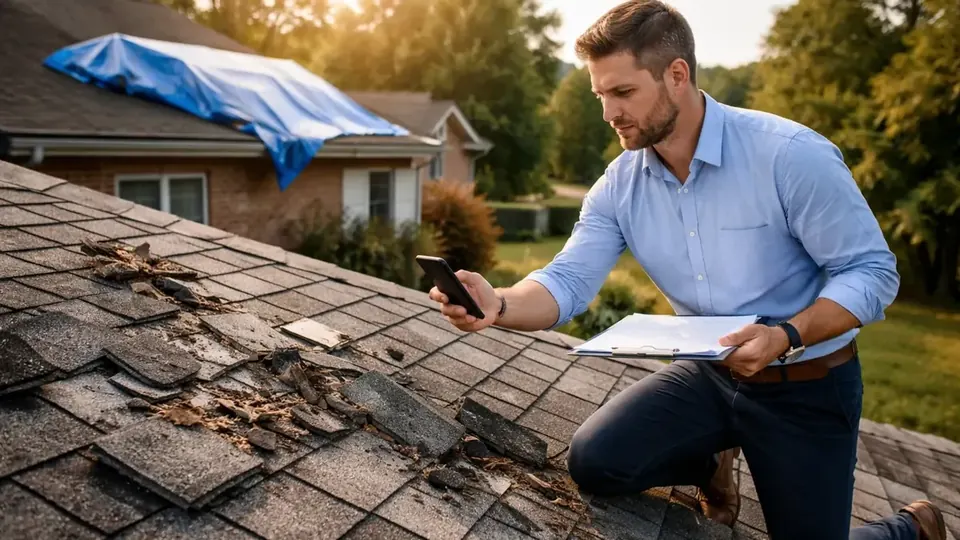
Property damage can upend a household or a business in minutes. The insurance claim that follows should not make things worse, but for many Port Arthur property owners it does. Policies are dense, adjusters rotate, deadlines stack up, and after a hurricane there may be two or three different insurers involved. As a Port Arthur public adjuster, we provide policyholder representation for a wide range of property insurance claims: we handle the inspection, documentation, estimating, and negotiation so you can focus on recovery, not paperwork.
The cards above link to each service. Below is an overview of how those services fit together.
Residential and commercial claim representation
A property claim is more than a phone call to report damage. It requires accurate valuation, a careful reading of the policy, and steady communication with the insurer. We represent both homeowners and business owners across Port Arthur and Jefferson County, including:
- Single-family homes and multi-unit residences
- Retail, office, industrial, and mixed-use buildings
- Owner-occupied and tenant-occupied properties
Homeowners can learn more on our residential property claims page. Businesses and property managers should see commercial property claims, which covers issues such as metal buildings, low-slope roofs, and business income losses, including interruptions tied to the port and refinery shutdowns after a storm.
Hurricane, TWIA, wind, and storm claims
Gulf hurricanes and tropical storms drive the largest claims in Southeast Texas. Jefferson County is a first-tier coastal county in the Texas Windstorm Insurance Association (TWIA) area, so many owners carry wind and hail coverage through TWIA rather than their homeowners policy. We help with:
- Hurricane damage claims, where named-storm deductibles and wind-versus-flood questions often arise
- TWIA windstorm claims, with their own filing deadlines, appraisal rules, and WPI-8 repair requirements
- Wind damage claims from tropical systems and severe thunderstorms with straight-line winds
- Storm damage claims involving several causes at once, including tornadoes spun up by tropical systems
- Hail damage claims, which are less frequent here than inland but still occur in spring storms
- Roof damage insurance claims, from repair-versus-replace disputes to code and windstorm items
Weather records can support a storm claim. Use our storm lookup tool or hurricane tracker to see what was reported or forecast near you.
Flood, water intrusion, and mold claims
Water losses are among the most misunderstood claims, and Southeast Texas sees more than its share. Harvey in 2017 and Imelda in 2019 both brought extreme rainfall to Jefferson County. Coverage often depends on where the water came from and how quickly the damage happened. We assist with:
- Flood damage claims under NFIP or private flood policies, including rising water and storm surge
- Water damage claims from wind-driven rain through damaged roofs, windows, or walls, and from burst pipes, including freeze-related breaks like those in February 2021
- Roof leaks and drainage problems
- Mold damage claims, where mold develops as secondary damage and the policy provides coverage, often subject to a sublimit
Standard homeowners, commercial, and TWIA policies generally exclude flood; flood coverage usually comes from the National Flood Insurance Program or a private flood policy. Read wind vs. flood damage in Port Arthur for how the two are separated.
Fire and smoke damage
Fire damage does not end when the flames are out. Smoke, soot, and heat can affect framing, wiring, HVAC systems, and contents in ways that are not obvious at first, and water used to fight the fire adds another layer of damage. Fire-related claims we work on include structural fire damage, smoke and soot contamination, water damage from firefighting, odor problems, and partial or total losses. See fire damage claims and smoke damage claims.
Additional covered losses
Not every loss fits neatly into one category. We also review claims involving structural collapse, theft and vandalism, vehicle or tree impact, and damage to equipment and contents. If you are unsure whether a loss is covered, we can read your policy with you and explain your options before a costly mistake is made.
Denied, underpaid, and delayed claims
Many people contact us after something has already gone wrong. We help with:
- Denied insurance claims, by reviewing the denial reasons against the policy and the evidence
- Underpaid insurance claims, where the scope, pricing, or line items do not match the damage
- Delayed insurance claims, measured against the timelines in the Texas Prompt Payment of Claims statute or TWIA's own statutory timelines
- Insurance estimate reviews, a line-by-line comparison of the insurer's estimate with the actual damage
Read more in what to do after a denied insurance claim in Port Arthur.
Reopening previously settled claims
Many policyholders assume a closed claim is final. Often it is not. Depending on the policy and the timeline, a claim may be supplemented or reopened when:
- Additional damage surfaced later
- Repairs uncovered hidden damage, such as wet insulation or mold behind walls
- Pricing or scope in the original estimate was incomplete
- The payment did not reflect real repair costs
Our insurance claim supplements service addresses these situations. When the disagreement is over the amount of the loss rather than coverage, the policy's insurance appraisal clause may also be an option. Check your policy for deadlines, and consult a Texas attorney about any deadline to file suit.
How our service process works
Every claim is different, but our approach is consistent:
- Free Claim Review of your situation, policies, and any insurer documents
- Written contract with fees disclosed up front
- Property inspection and damage assessment
- Policy and coverage analysis across every applicable policy
- Detailed documentation and estimate
- Claim submission or supplement
- Ongoing negotiation and follow-up through resolution
You will always know who is handling your claim and what comes next.
When professional representation makes sense
You do not need a public adjuster for every claim. Consider professional help if your claim is delayed or disputed, the offer does not cover repairs, the insurer keeps requesting more information, the documentation requirements feel overwhelming, or the damage is extensive or hidden. Earlier involvement can prevent missteps, but we can step in at most points in the process.
Serving Port Arthur property owners
Port Arthur's climate, building styles, and insurance market create their own challenges, from wind-damaged composition shingles on older pier-and-beam homes to low-slope roofs on commercial and industrial buildings. Our goal is the same on every file: fair claim handling backed by accurate documentation and informed negotiation. We serve Port Arthur and the communities listed on our service areas page.
Ready to talk about your claim? Request a Free Claim Review or call +1 (832) 503-5866.
Frequently Asked Questions
What types of claims does a Port Arthur public adjuster handle?
We work on residential and commercial property insurance claims, including hurricane, TWIA windstorm, wind, storm, flood, roof, hail, water, mold, fire, and smoke damage, as well as claims that have been denied, underpaid, or delayed. We do not handle auto, health, or liability claims.
Do I need a public adjuster for every claim?
No. Small, straightforward claims are often resolved fairly without outside help. Representation tends to make the most sense when the loss is large or complex, several policies are involved, the claim is disputed, or the insurer's estimate does not cover the actual repair scope.
Can you handle my TWIA, homeowners, and flood claims together?
We can help you coordinate them. After a hurricane, a Port Arthur property may have separate claims with TWIA for wind, a homeowners insurer for other covered perils, and an NFIP or private flood insurer for rising water. Each has its own adjuster, deductible, and rules, and keeping the damage clearly separated by cause is important.
Can you help after my claim was already paid or closed?
Often, yes. Many policies allow supplemental or reopened claims when additional damage is found or the original scope was incomplete, subject to policy and statutory deadlines. We review the file and tell you honestly whether further recovery looks possible.
How are your fees set?
Fees are disclosed in a written contract before any work begins; Texas law caps public adjuster compensation at 10% of the insurance settlement. The Free Claim Review has no cost and no obligation.
Do you only work in Port Arthur?
We serve Port Arthur, Jefferson County, and surrounding Southeast Texas communities, including Beaumont, Nederland, Groves, Port Neches, Sabine Pass, and Orange. See our service areas page for more.